AustinIO > AI Data Center Exemplars > Nexus Hubbard
Nexus Hubbard
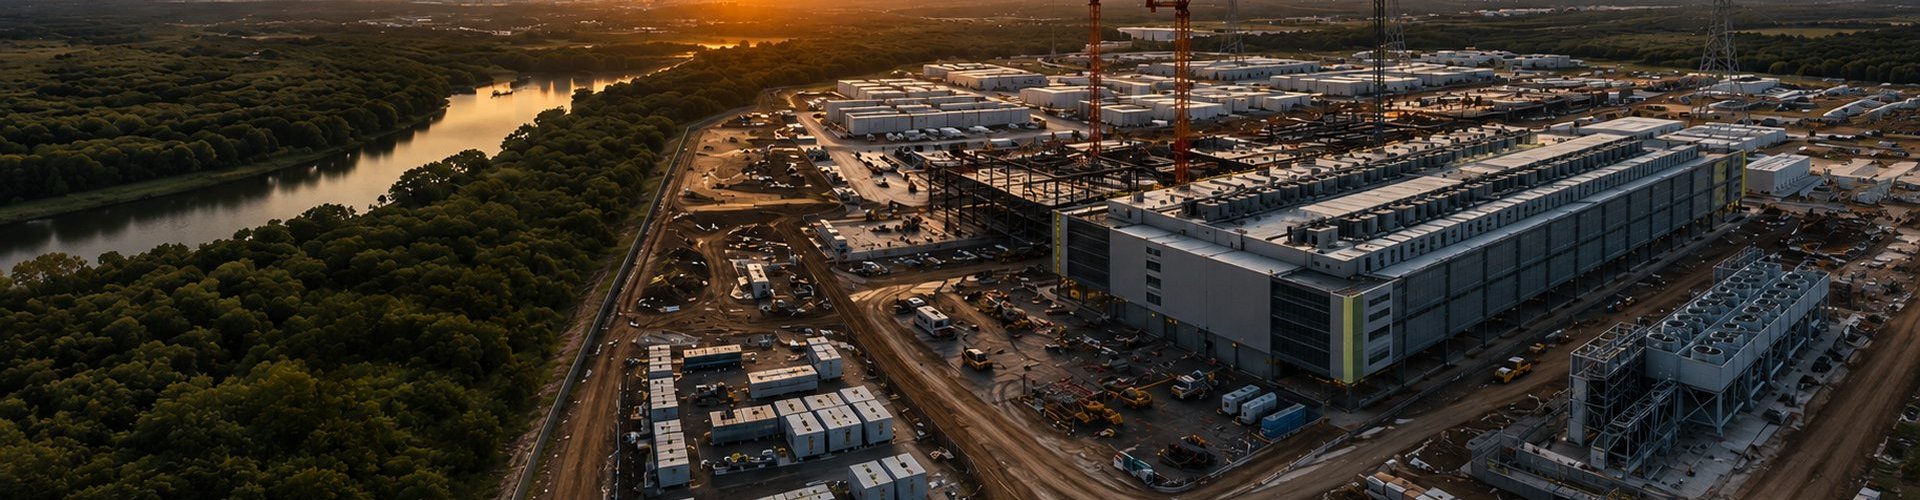
Nexus Hubbard is the exemplar of a financing structure, not an energy model: a campus where the developer builds, the lab occupies, and a hyperscaler guarantees the whole thing. Nexus Data Centers built it speculatively, Anthropic is the compute tenant, and Google guarantees the lease and power obligations for roughly 20% equity. It answers the question of how a lab gets multi-gigawatt compute without owning any of it.
| Attribute | Detail |
|---|---|
| Developer / owner | Nexus Data Centers |
| Tenant | Anthropic (compute) |
| Guarantor | Google (~20% equity, lease and power guarantor) |
| Location | Hubbard, Hill County, TX |
| Distance from Austin | ~130 mi N |
| Capacity | ~500 MW initial across four leases; site ultimate stated at 7.7 GW |
| Campus | 2,800 acres, near a major gas pipeline |
| Power model | Behind-the-meter, on-site gas (1.6 GW initial generation) |
| Compute chip | Google TPU (Ironwood) |
| Known tenants / workloads | Anthropic (contracted compute tenant) — a sourced fact, not an inference |
| Investment | ~$5B initial (Anthropic); Google guarantee effective on completion |
| Timeline | Nexus built speculatively from early 2025; Anthropic signed Mar 2026; initial online Q4 2027 |
| Status | Under construction |
Why it exists here
Hubbard sits in Hill County on 2,800 acres near a major natural gas pipeline — the fuel supply for on-site generation. What makes it an exemplar is not the location but the deal. Nexus Data Centers began building the campus speculatively in early 2025, before it had a tenant, betting that AI compute demand would arrive faster than anyone could permit a greenfield site. Anthropic signed in March 2026, and Google stepped in behind the lease.
The structure
Three parties, three roles. Nexus develops and owns the campus. Anthropic is the compute tenant across four separate leases covering roughly 500 MW initially, against a stated site ultimate of 7.7 GW. Google guarantees the lease and power obligations — effective on completion — in exchange for roughly 20% project equity, and Anthropic runs Google TPUs (Ironwood generation) on the site rather than Nvidia hardware.
The novelty is that financial risk is decoupled from operation. Google carries the guarantee on a campus it does not run, for a lab that competes with it directly in frontier models, because the arrangement secures TPU deployment and a share of the asset. This is distinct from Hut 8 Beacon Point's four-party compute-supply chain: Hubbard is a three-party financing guarantee, where Google underwrites; Beacon Point is a disaggregated operating stack, where each layer sells to the next. Two different answers to the same question of how a lab gets compute without owning infrastructure.
The power model
Hubbard is behind-the-meter on on-site gas, with 1.6 GW of initial generation drawn from the adjacent pipeline. The 7.7 GW ultimate figure is the campus's stated full-build ceiling, not committed capacity; the 500 MW across four leases is what Anthropic has contracted so far. As always, the large number is the horizon and the small number is the commitment.
What runs here
Hubbard is the strongest lab-tenant case in Texas because the tenant is named and contracted: Anthropic buys the compute, so Anthropic workloads run here as a sourced fact rather than an inference from the chips. The chips themselves — Google TPUs — reinforce it, since the Google guarantee and TPU deployment are the same deal. What stays private, as everywhere, is which specific Anthropic models or runs execute on this campus versus Anthropic's other Texas sites.
Where it fits
Hubbard is the financing-structure exemplar of the set. Where the hyperscaler campuses show operators building for themselves and the merchant campuses show developers building for whoever comes, Hubbard shows the newest arrangement: a lab with no infrastructure, a developer with no tenant risk, and a hyperscaler underwriting both to place its own silicon. Read alongside Beacon Point, it shows the compute-supply structure is still being invented deal by deal.
Last updated September 11, 2026. Structure and figures reflect reported terms; the 7.7 GW ultimate is a stated ceiling, not committed capacity. Status: under construction, initial capacity Q4 2027.
Related: Behind-the-Meter Power · Water & Cooling · ERCOT Large Load Interconnection · Brownfield Inheritance · AI Data Center Exemplars